Why Nigeria Needs Stronger Oversight of MDAs
July 3, 2026
Rotary Club of Ipaja New Dawn 2026 Handover Fellowship: A New Era of Service, Leadership & Community Impact in Lagos
July 3, 2026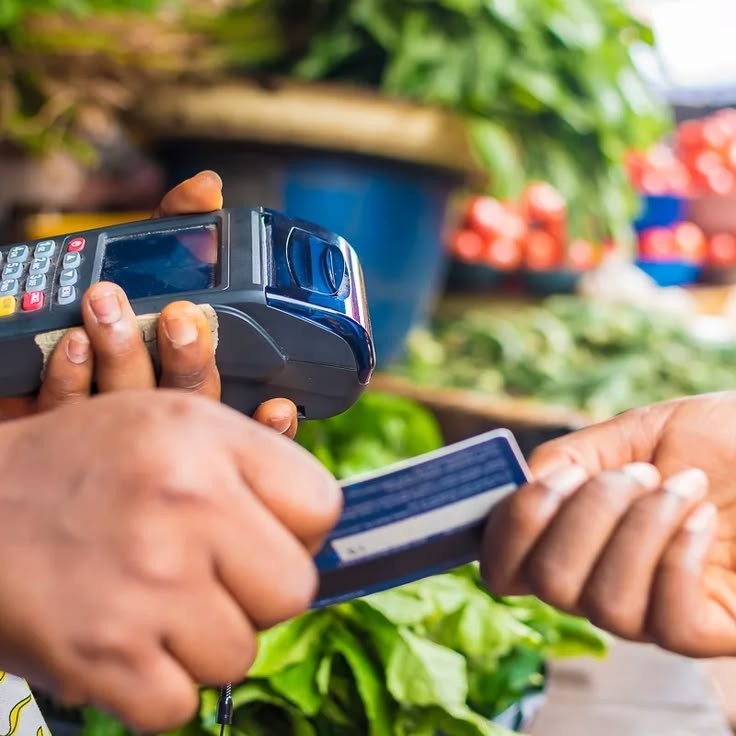
Introduction: Advancing Nigeria’s Cashless Future
Nigeria’s cashless policy rests on a compelling rationale. Heavy dependence on physical cash carries significant costs: the expense of printing, distributing, and securing cash; the inefficiency and insecurity of cash transactions; the difficulty of tracking cash-based economic activity; and the exclusion of cash-based economic life from the formal financial system.
Reducing cash dependence and encouraging digital payment alternatives promises to address these costs, improving efficiency, transparency, and financial inclusion across the economy.
These benefits make the cashless transition a worthy policy goal. The challenge has always been translating these policy goals into practical reality.
The Rationale for a Cashless Economy
Nigeria’s cashless policy rests on a compelling rationale.
Heavy dependence on physical cash carries significant costs: the expense of printing, distributing, and securing cash; the inefficiency and insecurity of cash transactions; the difficulty of tracking cash-based economic activity; and the exclusion of cash-based economic life from the formal financial system.
Reducing cash dependence and encouraging digital payment alternatives promises to address these costs, improving efficiency, transparency, and financial inclusion across the economy.
These benefits make the cashless transition a worthy policy goal.
A more cashless economy would be more efficient, with lower transaction costs and greater speed.
It would be more transparent, with digital transactions generating records that support accountability and reduce illicit activity.
And it would be more inclusive, bringing more economic activity into the formal financial system.
The cashless policy is, in this sense, a reform with significant potential benefits, aligned with Nigeria’s broader goals of efficiency, transparency, and inclusive development.
The challenge has always been translating these policy goals into practical reality.
The Challenge of Cashless Transition
Despite its compelling rationale, the transition to a cashless economy has proven challenging in Nigeria.
Cash remains deeply embedded in Nigerian economic life, particularly in the informal economy and among populations underserved by formal finance.
The transition requires not just policy directives but the practical infrastructure and trusted tools that make digital payments genuinely accessible and attractive to ordinary Nigerians.
Where these tools are absent or where trust in them is lacking, the cashless transition stalls, regardless of policy intentions.
This challenge highlights the importance of the practical tools and platforms through which the cashless transition actually happens.
Policy can set goals and create incentives, but the transition ultimately depends on ordinary Nigerians adopting digital payment tools in their daily economic lives.
This adoption depends on the tools being accessible, trustworthy, and genuinely useful.
The cashless transition therefore requires not just policy but the development and adoption of the digital financial tools that make cashless economic life practical and attractive for ordinary people, including those currently underserved by formal finance.
How Community Wallets Support the Transition
Community-based digital wallets, like the SINNTS Wallet, are natural allies of the cashless transition because they provide exactly the accessible, trusted digital payment tools that the transition requires.
By offering digital financial functionality within trusted community contexts, they make digital payments accessible and attractive to ordinary Nigerians, including those who might resist standalone digital payment products.
In doing so, they advance the practical adoption of digital payments on which the cashless transition depends.
The community-based character of these wallets is particularly valuable for the cashless transition.
Much of the resistance to digital payments comes from unfamiliarity and lack of trust, barriers that community embedding directly addresses.
When digital payment tools arrive within a trusted community context, the trust and familiarity of that context lower the barriers to adoption.
The SINNTS Wallet, by providing digital payment functionality within a trusted community platform, helps to overcome the resistance that has slowed the cashless transition, advancing the practical adoption of digital payments among populations that policy alone has struggled to reach.
Reaching the Cash-Dependent
A particular strength of community-based digital wallets in supporting the cashless transition is their ability to reach the cash-dependent populations that the transition most needs to include.
The informal economy, the unbanked, and other cash-dependent populations have been among the most resistant to the cashless transition, both because they are underserved by formal digital finance and because of the unfamiliarity and lack of trust that inhibit adoption.
Community-based wallets, with their accessibility and trusted community contexts, are well positioned to reach exactly these populations.
By reaching the cash-dependent through accessible, trusted digital tools, community-based wallets advance the cashless transition where it has been most difficult.
This contribution is significant because the success of the cashless policy ultimately depends on including the cash-dependent populations that have resisted the transition.
The SINNTS Wallet, by reaching these populations through community-embedded digital finance, helps to extend the cashless transition to the parts of the economy where it has been slowest, supporting the broader policy goal of reducing cash dependence across the entire economy, not just among the already-banked.
A Partnership for Progress
The relationship between community-based digital wallets and Nigeria’s cashless policy is fundamentally one of partnership.
The cashless policy sets the goals and creates the enabling environment; community-based wallets provide the practical tools through which the transition actually happens at the level of ordinary economic life.
Each supports the other: the policy creates the context in which digital wallets can flourish, and the wallets provide the practical means through which the policy’s goals are realised.
This partnership is a natural and mutually reinforcing one.
Recognising and strengthening this partnership could accelerate Nigeria’s cashless transition.
An environment that supports the development of community-based digital wallets, that recognises their contribution to the cashless agenda, helps to realise the policy’s goals.
The SINNTS Wallet, as an example of community-based digital finance that advances the cashless transition, represents a natural ally in this national effort.
As Nigeria pursues its cashless policy, the community-based digital finance that platforms like SINNTS provide deserves recognition as a genuine partner in the transition toward the more efficient, transparent, and inclusive cashless economy that the policy seeks to build.
