Closing Nigeria’s Financial Inclusion Gap: The Role of the SINNTS Wallet
July 1, 2026How Nigeria Can Achieve Better Intergovernmental Relations
July 2, 2026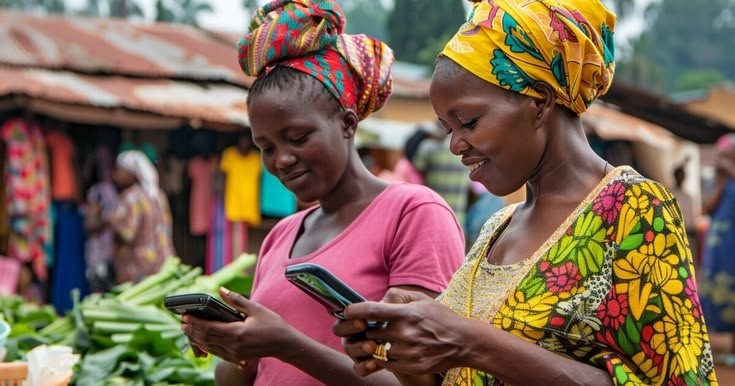
Introduction: Bringing Financial Participation to Every Nigerian
The unbanked are people who operate entirely outside the formal financial system, without bank accounts or access to formal financial services.
In Nigeria, they number in the tens of millions and include some of the most economically active members of society: market traders, artisans, farmers, informal sector workers, and small entrepreneurs.
They are not economically inactive, far from it, but they conduct their economic activity in cash, outside the formal financial system, lacking access to the tools that could make their economic lives more secure and productive.
Bringing these millions into the financial system is not only a matter of inclusion but also a key step toward building a stronger, more resilient, and more inclusive digital economy.
Who Are the Unbanked?
The unbanked are people who operate entirely outside the formal financial system, without bank accounts or access to formal financial services.
In Nigeria, they number in the tens of millions and include some of the most economically active members of society: market traders, artisans, farmers, informal sector workers, and small entrepreneurs.
They are not economically inactive, far from it, but they conduct their economic activity in cash, outside the formal financial system, lacking access to the tools that could make their economic lives more secure and productive.
The unbanked are not a homogenous group, but they share certain characteristics.
They are disproportionately poor, rural, female, and engaged in the informal economy.
They often lack the documentation that formal banking requires, live far from bank branches, or find formal financial institutions intimidating and alien.
Many have never had a reason to interact with formal finance and see no clear path to doing so.
Understanding who the unbanked are, and why they remain outside the financial system, is essential to designing approaches that can genuinely bring them into financial participation.
Why Banking the Unbanked Matters
Bringing the unbanked into the financial system matters for both the individuals concerned and the broader economy.
For individuals, financial inclusion opens doors: the ability to save securely, to access credit, to make and receive payments efficiently, and to build the financial history that enables further opportunity.
These capabilities can transform economic lives, providing security against shocks, enabling investment in education and enterprise, and supporting economic advancement.
Financial inclusion is, for many of the unbanked, a genuine pathway out of economic precarity.
For the broader economy, banking the unbanked unlocks significant benefits.
It brings more economic activity into the formal system, improving efficiency and generating valuable economic data.
It enables the unbanked to participate more fully in the economy, activating their productive potential.
And it supports the broader goals of inclusive growth and poverty reduction.
The financial inclusion of the unbanked is therefore not just a matter of individual benefit but of national economic interest, central to building the inclusive, broadly prosperous economy that Nigeria’s development requires.
The Digital Pathway to Inclusion
Digital technology has opened a new pathway to banking the unbanked, one that overcomes many of the barriers that traditional banking faced.
Digital financial tools can be accessed from a smartphone without visiting a physical branch, overcoming the barrier of geographic distance.
They can operate with lower documentation requirements than formal banks, overcoming the barrier of documentation.
And they can reach populations through the mobile networks that already connect even remote communities.
This digital pathway has already brought millions into financial participation through mobile money and digital wallets.
Community-based digital platforms extend this digital pathway further by embedding financial tools within trusted community contexts.
The SINNTS Wallet exemplifies this approach, offering digital financial functionality within a community platform that users already trust and engage with.
This combination, of digital accessibility and community trust, is particularly powerful for reaching the unbanked, who are often excluded not only by practical barriers but by the unfamiliarity and intimidation of formal finance.
By offering financial tools within a trusted, familiar context, community-based digital platforms can bring the unbanked into financial participation in ways that overcome both practical and psychological barriers.
How SINNTS Reaches the Excluded
SINNTS reaches the unbanked through several features that address the specific barriers excluding them.
Its wallet is accessible from any smartphone, overcoming geographic barriers.
It operates within a community context that provides the trust and familiarity that lower psychological barriers.
And it connects financial participation to the broader community engagement that draws people to the platform, giving the unbanked a natural reason to access financial tools that they might not seek out in a formal banking context.
These features make the platform genuinely accessible to populations that formal banking has struggled to reach.
Crucially, SINNTS brings the unbanked into financial participation as a natural extension of their community engagement, rather than as a separate, intimidating step.
The unbanked person who joins SINNTS for its community features finds financial tools available within that familiar context, lowering the threshold to financial participation.
This integration of finance with community engagement is one of the most effective ways to reach the unbanked, who often resist standalone financial products but readily adopt financial tools that arrive within a context they already trust and value.
By integrating finance with community, SINNTS creates a natural and accessible pathway to financial inclusion for the excluded.
Bringing Millions Into the Digital Economy
The opportunity to bank the unbanked through community-based digital platforms is substantial.
Nigeria’s tens of millions of unbanked represent an enormous reserve of economic potential that financial inclusion could activate.
By bringing these millions into financial participation, through accessible, trusted, community-based digital tools, platforms like SINNTS could make a significant contribution to financial inclusion and to the broader goals of inclusive growth and economic development that depend on it.
Realising this opportunity requires the growth and adoption of community-based digital financial platforms, supported by an environment that enables their development.
As these platforms reach the unbanked and bring them into the digital economy, they advance one of Nigeria’s most important development goals while activating the economic potential of millions of excluded Nigerians.
Banking the unbanked is a great challenge and a great opportunity, and the community-based digital finance that platforms like SINNTS represent offers a genuinely promising path toward bringing Nigeria’s excluded millions into the digital economy and the financial participation that economic citizenship requires.
