Improving Transparency in Nigeria’s Oil and Gas Sector
July 1, 2026Banking the Unbanked: How SINNTS Brings Millions Into the Digital Economy
July 2, 2026
Introduction: The Importance of Financial Inclusion
Financial inclusion remains a significant challenge in Nigeria despite years of effort to address it.
A substantial portion of the adult population remains either entirely outside the formal financial system or inadequately served by it, lacking access to the bank accounts, savings facilities, credit, and payment services that enable full economic participation.
This exclusion falls most heavily on the poor, on rural populations, on women, and on those working in the informal economy, the very groups whose inclusion matters most for equitable development.
Closing the financial inclusion gap is therefore not merely a technical financial objective but a matter of economic justice and opportunity, central to the broader goal of inclusive development.
The Scale of Financial Exclusion
Financial exclusion remains a significant challenge in Nigeria despite years of effort to address it.
A substantial portion of the adult population remains either entirely outside the formal financial system or inadequately served by it, lacking access to the bank accounts, savings facilities, credit, and payment services that enable full economic participation.
This exclusion falls most heavily on the poor, on rural populations, on women, and on those working in the informal economy, the very groups whose inclusion matters most for equitable development.
The consequences of financial exclusion are serious.
Without access to formal financial services, people struggle to save securely, to access credit, to make and receive payments efficiently, and to build the financial history that opens doors to further opportunity.
Financial exclusion traps people in cash-based economic lives that are less secure, less efficient, and less able to support economic advancement.
Closing the financial inclusion gap is therefore not merely a technical financial objective but a matter of economic justice and opportunity, central to the broader goal of inclusive development.
Why Traditional Approaches Fall Short
Efforts to close the financial inclusion gap have traditionally focused on extending the formal banking system to underserved populations, opening branches, offering accounts, and encouraging the unbanked to enter the formal system.
While these efforts have achieved real progress, they have also encountered persistent limitations.
The barriers that exclude people from formal finance, geographic distance, documentation requirements, minimum balances, and the cultural distance between formal institutions and community-based economic life, have proven stubborn, leaving many still excluded despite years of effort.
These persistent limitations suggest that closing the financial inclusion gap requires more than extending the traditional banking model; it requires approaches that work differently, that meet underserved populations where they are rather than requiring them to conform to systems not designed for them.
Digital financial tools embedded in community platforms represent exactly such an alternative approach.
By providing financial functionality within trusted community contexts, with lower barriers than formal banking, they reach populations that traditional approaches have struggled to include, offering a genuinely different path toward financial inclusion.
The Community-Based Approach
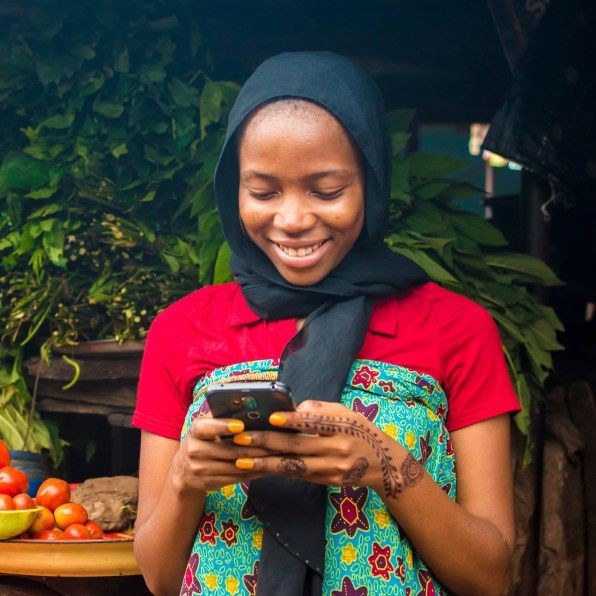
The SINNTS Wallet exemplifies a community-based approach to financial inclusion that addresses many of the limitations of traditional banking.
Rather than requiring people to enter a formal institution that may feel distant and alien, it provides financial functionality within a community platform that users already trust and engage with.
This community embedding is crucial: it provides the trust and familiarity that lower the barriers to financial participation, allowing people who would never enter a formal bank to access digital financial services within a context that feels natural and trustworthy.
This community-based approach aligns with the way financial life has always worked in many Nigerian communities, through trusted relationships, community accountability, and the social structures that organise economic activity.
The traditional savings groups that have long served Nigerian communities embody this community-based approach to finance, building on trust and social connection rather than formal institutional structures.
By translating this community-based model into the digital realm, the SINNTS Wallet offers an approach to financial inclusion that is culturally familiar and that reaches populations excluded by formal banking, addressing the inclusion gap from a different and promising direction.
Lowering the Barriers to Participation
The SINNTS Wallet helps to close the financial inclusion gap by lowering the barriers that exclude people from financial participation.
Where formal banking often requires documentation that many lack, the wallet offers more accessible entry.
Where formal banking requires visiting physical branches that may be distant, the wallet is accessible from any smartphone.
Where formal banking can feel intimidating and alien, the wallet arrives within a trusted community context.
These lower barriers make financial participation accessible to populations that formal banking has struggled to reach.
This barrier-lowering is the key to the wallet’s contribution to financial inclusion.
The financial inclusion gap persists largely because of barriers, of documentation, distance, cost, and cultural distance, that exclude people from formal finance.
By lowering these barriers, community-based digital finance brings into financial participation people who would otherwise remain excluded.
The SINNTS Wallet, by offering accessible financial functionality within a trusted community context, directly addresses the barriers that maintain the financial inclusion gap, offering a practical means of bringing excluded populations into digital financial participation.
Toward Universal Financial Participation
The goal of financial inclusion is, ultimately, universal financial participation:
A Nigeria in which all citizens have access to the financial services that enable full economic participation and opportunity.
Achieving this goal requires a range of approaches working together, formal banking, mobile money, agent networks, and community-based digital finance, each reaching different populations and addressing different barriers.
Community-based digital finance, exemplified by the SINNTS Wallet, represents an important component of this larger effort, reaching populations that other approaches struggle to include.
As Nigeria works toward universal financial participation, the contribution of community-based digital finance deserves recognition and support.
By reaching the excluded through trusted community contexts and lower barriers, platforms like SINNTS advance the financial inclusion agenda in ways that complement other approaches.
Closing Nigeria’s financial inclusion gap is a national priority of profound importance, and the community-based digital finance that the SINNTS Wallet represents offers a genuine and promising path toward bringing excluded Nigerians into the financial participation that full economic citizenship requires.
